Top Solar Panel Manufacturers (2026 Data): Shipments, Profits and Factories
Updated: October 2026 · Data year: 2025, with H1 2026 where published · Primary sources: company annual results and filings, InfoLink, IEA PVPS, Wood Mackenzie, SEIA, Mercom
Key figures
- 311 GW: modules shipped in 2025 by JinkoSolar, LONGi, Trina Solar and JA Solar, 44% of the world's 706 GW (list.solar calculation)
- CNY 25 billion: their combined 2025 net loss, about US$3.6 billion
- 29.3%: First Solar's 2025 net margin, the highest of any large panel maker ($1.53 billion on $5.22 billion of sales)
- 1,531 GW vs 722 GW: global module manufacturing capacity against actual production in 2025, a utilisation rate of about 47% (IEA PVPS)
- −31%: year-on-year fall in top-10 module shipments in H1 2026, the first sharp drop in InfoLink's ranking
- 79%: China's share of world module production in 2025, down from 86% in 2024 (IEA PVPS)
The four companies that make most of the world's solar panels have never shipped more, or earned less. JinkoSolar, LONGi, Trina Solar and JA Solar delivered about 311 GW of modules in 2025, 44% of everything shipped worldwide. Together they lost about CNY 25 billion. JinkoSolar's gross margin for the year was 2.2%, and 0.3% in the fourth quarter.
The most profitable panel maker of any size is in Tempe, Arizona. First Solar earned $1.53 billion on $5.22 billion of sales by making thin-film modules in the US, India, Malaysia and Vietnam, outside the price war altogether. India's Waaree and Premier Energies also made money, selling mostly to the US. This edition ranks 16 manufacturers by what they shipped, what they earned and where they build, using 2025 annual results and H1 2026 shipment data. It replaces a 2020 list, several of whose companies have since left the business.
Top Solar Panel Manufacturers by 2025 Shipments
InfoLink's 2025 ranking put the 12 largest suppliers at 536 GW combined, with JinkoSolar and LONGi tied at the top and Trina and JA Solar tied behind them. TOPCon cells accounted for about 95% of the modules these companies shipped, and PERC for 1–2%. The table uses each company's own reported volumes, which InfoLink publishes only as ranges.
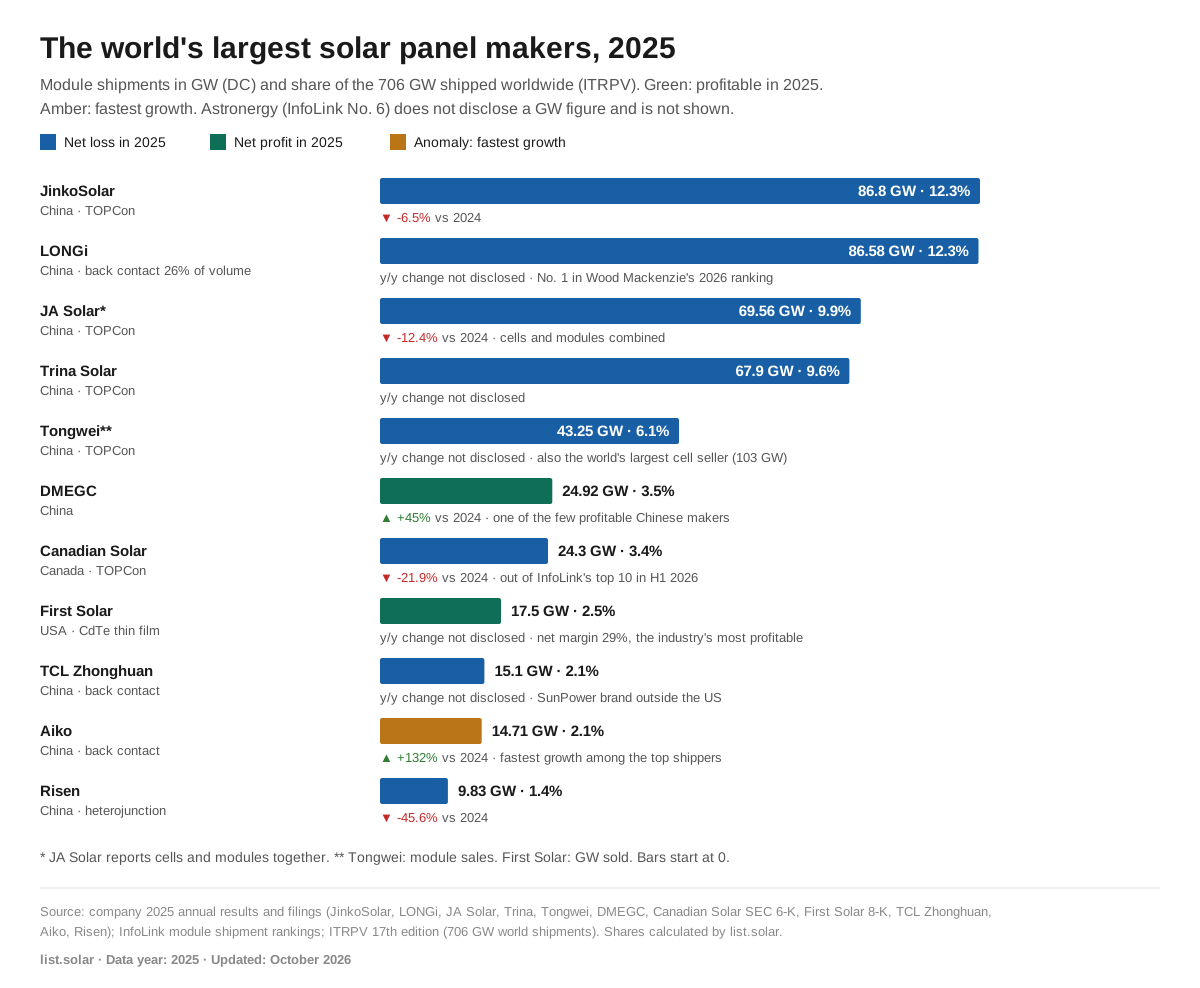
| Rank 2025 | Manufacturer | HQ · listing | 2024 (GW) | 2025 (GW) | Change y/y | Share of world, 2025 | InfoLink rank, H1 2026 |
|---|---|---|---|---|---|---|---|
| 1 | JinkoSolar | China · NYSE: JKS, SSE: 688223 | 92.87 | 86.8 | −6.5% | 12.3% | 1 (tied) |
| 2 | LONGi | China · SSE: 601012 | n/a | 86.58 | n/a | 12.3% | 1 (tied) |
| 3 | JA Solar* | China · SZSE: 002459 | 79.45 | 69.56 | −12.4% | 9.9% | 4 |
| 4 | Trina Solar | China · SSE: 688599 | n/a | 67.9 | n/a | 9.6% | 3 |
| 5 | Tongwei** | China · SSE: 600438 | n/a | 43.25 | n/a | 6.1% | 5 |
| 6 | Astronergy (Chint) | China · unlisted | n/a | 30–50 (range) | n/a | n/a | 6 |
| 7 | DMEGC | China · SZSE: 002056 | 17.2e | 24.92 | +45% | 3.5% | 8 (tied) |
| 8 | Canadian Solar | Canada · Nasdaq: CSIQ | 31.1 | 24.3 | −21.9% | 3.4% | outside top 10 |
| 9 | First Solar*** | USA · Nasdaq: FSLR | n/a | 17.5 | n/a | 2.5% | not ranked (thin film) |
| 10 | TCL Zhonghuan | China · SZSE: 002129 | n/a | 15.1 | n/a | 2.1% | 8 (tied, incl. DAS Solar) |
| 11 | Aiko | China · SSE: 600732 | 6.3e | 14.71 | +132% | 2.1% | 8 (tied) |
| 12 | Risen | China · SZSE: 300118 | 18.1e | 9.83 | −45.6% | 1.4% | outside top 10 |
GW DC, company-reported. * JA Solar reports cells and modules together. ** Tongwei: module sales. *** First Solar: GW sold. e = derived from the company's reported percentage change. Share = 2025 shipments ÷ 706 GW world shipments (ITRPV 17th edition), calculated by list.solar. Astronergy, which is unlisted, does not publish a figure; InfoLink places it in the 30–50 GW tier. GCL SI and Yingli also made InfoLink's 2025 top 12 without disclosing exact volumes. Sources: company results, InfoLink 2025 and H1 2026 rankings, ITRPV.
The ranking is shifting toward back-contact cells. LONGi sold 22.87 GW of back-contact modules in 2025, and Aiko 14.71 GW. In H1 2026, back-contact products made up about 16% of the top suppliers' shipments, against 83% for TOPCon. Aiko entered InfoLink's top 10 for the first time, and Canadian Solar dropped out of it for the first time.
Revenue and Profit: Who Makes Money Making Panels
Wood Mackenzie estimates that China's leading module makers lost a combined $5.5 billion in 2025, while most non-Chinese manufacturers stayed profitable. The table shows why scale stopped protecting anyone. Prices fell to about 9 US cents a watt, and every large Chinese producer except DMEGC ended the year in the red.
| Manufacturer | 2025 revenue | Change y/y | 2025 net result | Net margin |
|---|---|---|---|---|
| First Solar | $5.22 bn | +24% | +$1.53 bn | +29.3% |
| Premier Energies (FY26) | INR 8,026 cr | +20.7% | +INR 1,510 cr | +18.8% |
| Waaree Energies (FY26) | INR 26,536 cr | +84% | +INR 3,884 cr | +14.6% |
| DMEGC | CNY 22.58 bn | +21.7% | +CNY 1.85 bn | +8.2% |
| Canadian Solar | $5.60 bn | −6.6% | −$0.10 bn | −1.9% |
| GCL SI | CNY 15.34 bn | −5.5% | −CNY 1.17 bn | −7.6% |
| LONGi | CNY 70.35 bn | −14.8% | −CNY 6.45 bn | −9.2% |
| JA Solar | CNY 49.13 bn | n/a | −CNY 4.61 bn | −9.4% |
| JinkoSolar (Shanghai-listed unit) | CNY 65.49 bn | −29% | −CNY 6.88 bn | −10.5% |
| Trina Solar | CNY 66.98 bn | −16.6% | −CNY 7.03 bn | −10.5% |
| Tongwei | CNY 84.13 bn | −8.6% | −CNY 9.55 bn | −11.4% |
| Aiko | CNY 15.61 bn | +40% | −CNY 1.82 bn | −11.7% |
| TCL Zhonghuan | CNY 29.05 bn | +2.2% | −CNY 9.2 bn | −31.7% |
Net result attributable to shareholders. Indian companies: fiscal year April 2025–March 2026 (cr = 10 million rupees). JinkoSolar's NYSE-listed parent reported revenue of CNY 65.50 billion and a net loss of CNY 4.45 billion (−6.8%). LONGi's loss is derived from its 2024 loss and the reported reduction. TCL Zhonghuan includes its wafer business. Margins calculated by list.solar. Sources: company annual reports and filings (listed under Sources).
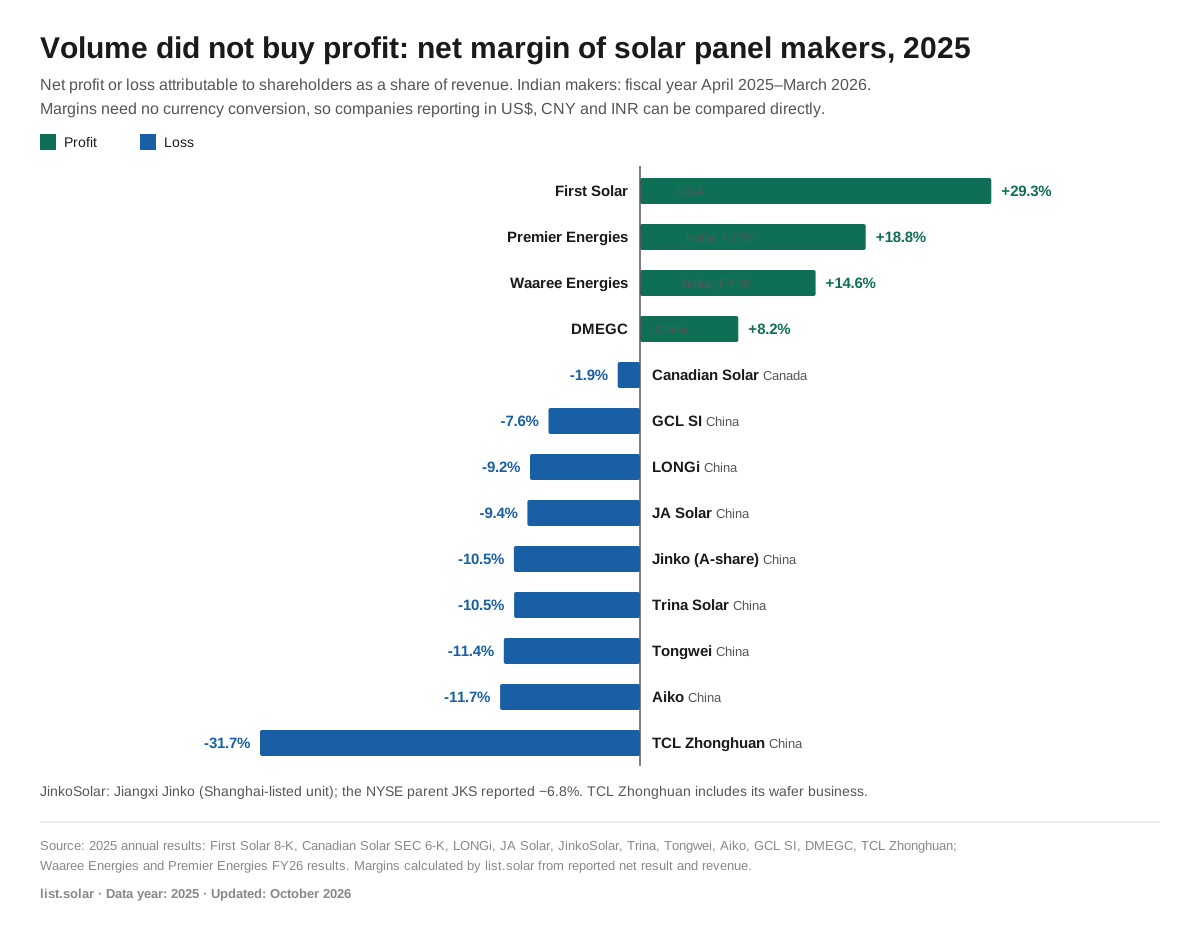
The profitable group shares one trait: each earns most of its money in markets protected from Chinese export prices. First Solar sells mainly in the US, where its 2026 guidance assumes $2.10–2.19 billion of Section 45X manufacturing tax credits. That is 84–88% of its expected gross margin, by list.solar's calculation. India's makers sell into a domestic market that requires locally listed modules for most projects, and into the US, which took 92% of India's module exports in H1 2026. Both advantages are policy-made, and both can move.
The Largest Solar Panel Manufacturers: Company Profiles
JinkoSolar: largest TOPCon maker, shrinking on purpose
JinkoSolar has shipped more than 220 GW of its Tiger Neo TOPCon modules since 2022 and led the world in 2024 with 92.87 GW. In 2025 it shipped 86.8 GW, revenue fell 29% and gross margin dropped to 2.2%. The company now plans to cut integrated capacity to about 100 GW by the end of 2026, including 14 GW outside China, and guides 2026 shipments at 75–85 GW. Its overseas footprint includes a 2 GW module plant in Jacksonville, Florida, and a 10 GW cell and module joint venture in Saudi Arabia announced in 2024. On 17 October 2026 it unveiled the Tiger Neo 5.0, a 25.52%-efficient back-contact rooftop module. RETC named JinkoSolar an Overall Highest Achiever for the seventh year running, the company says.
LONGi: the back-contact bet
While most rivals converted their lines to TOPCon, LONGi made back contact its main bet: 46 GW of HPBC 2.0 cell capacity in-house plus 11 GW through partners. Back contact made up 22.87 GW of its 86.58 GW of 2025 module sales and is planned at more than 65% of a roughly 80 GW target for 2026. Revenue fell 14.8% to CNY 70.35 billion, and the net loss narrowed to about CNY 6.45 billion from CNY 8.6 billion. Wood Mackenzie ranked LONGi first in its 2026 manufacturer ranking. In January 2026 LONGi took control of Jingkong Energy, its first big step into battery storage. In the US it holds a reduced stake in Illuminate USA, a 5 GW module joint venture with Invenergy in Ohio.
Trina Solar: panels plus storage
Trina shipped 67.9 GW in 2025, 95.8% of it n-type, on large 210 mm wafers. Revenue fell 16.6% to CNY 66.98 billion and the company lost CNY 7.03 billion, but the loss narrowed to CNY 283 million in Q1 2026. Its battery storage shipments doubled to more than 8 GWh. Trina sold its 5 GW Texas module plant to T1 Energy, which now runs it as G1_Dallas. It also holds the record for the largest certified perovskite-silicon tandem module, 27.2% on 1.52 m².
JA Solar: deepest cut to the 2026 plan
JA Solar runs 75–80 GW of cell and module capacity. In 2025 it shipped 69.56 GW of cells and modules (−12.4%) and lost CNY 4.61 billion on revenue of CNY 49.13 billion. After a first-half loss of CNY 2.66 billion, it cut its 2026 shipment target to about 50 GW on 28 August 2026, the sharpest retreat among the top four. Its first Middle East plant, 6 GW of cells and 3 GW of modules in Sohar, Oman, was still under development in H1 2026. JA was an RETC Overall Highest Achiever in 2026.
Tongwei: the world's largest cell seller
Tongwei started as a polysilicon producer and still sold 384,800 tonnes of it in 2025. It is also the largest seller of solar cells: 103.03 GW in 2025, up 17.5%. Its own module sales reached 43.25 GW, and overseas module sales rose 164% to 9.52 GW. Upstream exposure made it the biggest loser of 2025: CNY 9.55 billion, including CNY 5.02 billion of impairments, on revenue of CNY 84.13 billion. Its TW Solar modules were RETC Overall Highest Achievers and PVEL Top Performers in seven of eight categories in 2026.
Astronergy: the quiet No. 6
Astronergy belongs to Chint New Energy, which is majority-owned by Chint Electric. Because it is not listed on its own, it publishes no shipment or profit figures. InfoLink ranked it sixth in both 2025 and H1 2026, in the 30–50 GW tier. Its ASTRO N7 and N8 modules use zero-busbar TOPCon cells, and it makes cells and modules in Thailand as well as China.
Canadian Solar: from panels to American factories and batteries
Canadian Solar's module shipments fell 21.9% to 24.3 GW in 2025, and it dropped out of InfoLink's top 10 in H1 2026. Revenue was $5.60 billion and the net loss $104 million. The company is rebuilding around the US and storage. Its Mesquite, Texas, module plant is expanding from 5 GW to 10 GW in H2 2026, and its Jeffersonville, Indiana, heterojunction cell plant is planned at 6.3 GW in two phases. In December 2025 it formed CS PowerTech, 75.1% owned by the parent, to run the US plants directly. It no longer discloses global capacity. Its storage arm shipped 7.8 GWh in 2025 and reported a $3.6 billion backlog.
DMEGC: the profitable exception in China
DMEGC is a magnetics and components group with a solar business that brought in CNY 14.31 billion of its CNY 22.58 billion revenue in 2025. It shipped 24.92 GW of modules (+45%) from 23 GW of cell and 21 GW of module capacity, and earned a net profit of CNY 1.85 billion. It was the only large Chinese panel maker in the black. The company says US trade policy limits the profits of its overseas capacity.
Aiko: fastest growth, still loss-making
Aiko's all-back-contact (ABC) module shipments grew 132% to 14.71 GW in 2025 and now make up 68% of its revenue, which rose 40% to CNY 15.61 billion. Its Neostar 3P54 is one of the two most efficient rooftop panels on sale, at 25.0%. Growth has not yet brought profit: the net loss was CNY 1.82 billion. In February 2026 Aiko settled its back-contact patent dispute with Maxeon, taking a five-year licence for markets outside the US. In H1 2026 it entered InfoLink's top 10 for the first time.
TCL Zhonghuan (TCL Solar): wafers, SunPower and Maxeon
TCL Zhonghuan is one of the largest silicon wafer makers and, through Maxeon's former non-US business, the owner of the SunPower brand outside the US. It shipped 15.1 GW of modules in 2025 and lost about CNY 9.2 billion, the deepest margin loss in this ranking (−31.7%), a figure that includes its wafer business. It controls Maxeon, which has been under judicial management in Singapore since April 2026, and is buying 59% of DAS Solar for CNY 1.258 billion. InfoLink now counts DAS Solar inside TCL Solar. In October 2026 TCL SunPower launched the SunPower Origin back-contact panel in Europe with a 40-year warranty.
GCL SI: state tenders and a swing to loss
GCL System Integration, the module arm of the GCL group, says it ranked seventh worldwide by 2025 shipments, in line with InfoLink's list. Revenue fell 5.5% to CNY 15.34 billion and the company swung to a net loss of CNY 1.17 billion after a profit in 2024. It won more than 13 GW of tenders from Chinese state-owned utilities, and its module lines ran at more than 80% utilisation. An overseas plant is still at the planning stage.
First Solar: the profitable outlier
First Solar makes cadmium telluride (CdTe) thin-film modules, a technology no Chinese maker produces at scale, in factories in Ohio, Alabama, Louisiana, India, Malaysia and Vietnam. In 2025 it produced 16.1 GW, sold 17.5 GW and earned $1.53 billion on $5.22 billion of sales. Capacity reached about 23 GW at the end of 2025, about 13 GW of it in the US, after a 3.5 GW Louisiana plant came online. A 3.7 GW plant in South Carolina is announced. For 2026 it guides 17.0–18.2 GW and $4.9–5.2 billion of sales. In March 2026 the US International Trade Commission opened an investigation into First Solar's TOPCon patent complaint against JinkoSolar, Canadian Solar, Trina and T1 Energy, Qcells, Adani and others. In September First Solar moved to withdraw it in favour of federal lawsuits.
Qcells: Georgia's integrated supply chain
Hanwha Solutions' Qcells operates 8.6 GW of module capacity in Georgia: 5.1 GW in Dalton and 3.5 GW in Cartersville. Cartersville also holds 3.3 GW of ingot, wafer and cell lines, which started cell production in June 2026. The ramp was not smooth: in November 2025 Qcells furloughed about 1,000 Georgia workers after US Customs held its imported cells under the forced-labour law. Its renewables division reported an operating profit of KRW 62.2 billion in Q1 2026. Wood Mackenzie ranked Qcells tenth in 2026, and RETC named it an Overall Highest Achiever.
Waaree Energies: India's largest, built on US demand
Waaree runs about 26 GW of module and 5.4 GW of cell capacity in India and produced 12.6 GW of modules in fiscal 2026. Revenue rose 84% to INR 26,536 crore and net profit doubled to INR 3,884 crore. It has a 1.6 GW module plant in Texas and a 10 GW ingot and wafer plant under construction in Nagpur. The risk is concentration: the US bought 92% of India's module exports in H1 2026. In September 2026 the US set final duties on Indian solar imports of 123.04% (antidumping) and 126.09% (countervailing), and the International Trade Commission confirmed injury on 14 October.
Adani Solar: best test results, slower expansion
Adani Solar, part of Adani Enterprises, sold 4,904 MW of modules in fiscal 2026 from lines totalling 5.7 GW after a 1.7 GW addition in June 2026. Its "New Energy" segment earned INR 3,452 crore before tax. Adani was the only brand with Top Performer models in all eight categories of Kiwa PVEL's 2026 reliability Scorecard, and Wood Mackenzie ranked it sixth worldwide. Its 10 GW integrated target has slipped, and its Mundra plant was named in First Solar's patent complaint.
Premier Energies: cells before modules
Premier Energies grew revenue 20.7% to about INR 8,026 crore in fiscal 2026 and net profit 61% to about INR 1,510 crore. It runs 11.1 GW of module lines and is expanding cell capacity from 3.6 GW to 10.6 GW by September 2026. Cells are the bottleneck of India's supply chain, so that matters more than the module figure. Wood Mackenzie lists it among the 25 Grade A manufacturers.
Overcapacity: Twice the Factories the World Needs
The industry's losses come from one number. According to the IEA's PVPS programme, the world had about 1,531 GW of module manufacturing capacity in 2025 but produced 722 GW, a utilisation rate of about 47%. Installations were about 690 GW. China held 71% of the capacity and made 79% of the modules, down from 86% in 2024 as India, the US and Southeast Asia added plants. Wood Mackenzie puts utilisation at the top 10 producers higher, at 70%.
| Indicator | 2023 | 2024 | 2025 | 2026 | Change |
|---|---|---|---|---|---|
| Top-10 module shipments (InfoLink), GW | 413 | 502 | 536 (top 12) | 181.39 (H1, top 11) | +22% (2024); −31% top 10, H1 2026 y/y |
| Global module price (ITRPV), $/W | ~0.12 | 0.08 | 0.09 | 0.107 (TOPCon FOB China, 13 Oct) | +9% (2025) |
| World installations, GW | n/a | 566 (ITRPV) | 690 (IEA PVPS) | 612 forecast (SolarPower Europe) | −8% forecast for 2026 |
| China's share of module production | n/a | 86% | 79% | n/a | −7 pp |
Benchmarks come from different sources and are not strictly comparable year to year. 2023 price derived from ITRPV's reported 52% fall. Sources: InfoLink, ITRPV 16th and 17th editions, OPIS via pv magazine, IEA PVPS Trends 2026 via pv magazine, SolarPower Europe Global Market Outlook 2026–2030.
Beijing has tried to force consolidation. A plan for producers to buy out and idle about a third of polysilicon capacity was halted by the market regulator in January 2026, which banned coordination on output and prices. China scrapped its export VAT rebate for PV products from 1 April 2026, and a mandatory minimum-efficiency standard for modules takes effect on 1 January 2027. Demand is shrinking at home: China installed 97.19 GW in January–August 2026, down 57% year on year. SolarPower Europe expects the first global contraction in more than 20 years in 2026, to 612 GW.
Myth: The Biggest Manufacturer Is the Safest Choice
Buyers and installers often treat size as a guarantee that a manufacturer will be around to honour a 25- or 30-year warranty. The 2025 results argue against it. The four largest shippers lost about CNY 25 billion between them, JinkoSolar's gross margin was 2.2%, and JA Solar now expects to ship about 50 GW in 2026, roughly 28% less than in 2025. The most profitable makers were a mid-sized American thin-film producer and two Indian companies.
Size still brings scale in research, testing and service networks. But a warranty depends on the balance sheet behind it. Wood Mackenzie's ranking, which scores financial health alongside manufacturing and technology, gave only 25 of 48 assessed manufacturers a Grade A. For model-level quality, independent test programmes such as Kiwa PVEL and RETC matter more than shipment rank. Our best solar panels comparison covers those results by brand. The same logic applies to BloombergNEF's Tier 1 list, which measures bankability, not product quality.
Where Panels Are Made Outside China
Trade barriers have created two large manufacturing bases outside China, in the US and India. Both still depend on imported cells or wafers.
| Country | Module capacity | Cell capacity | Largest makers | Policy driver |
|---|---|---|---|---|
| United States | >60 GW (Oct 2025) | ~3 GW (Q1 2026) | First Solar (~13 GW), Qcells (8.6 GW), Canadian Solar (5 GW → 10 GW), Illuminate USA (5 GW), T1 Energy (5 GW) | 45X manufacturing credits; AD/CVD on Southeast Asia (2025) and India, Indonesia, Laos (2026); Section 232 tariff of 15% plus a $0.38/W minimum price from 4 Dec 2026 |
| India | 261.7 GW (June 2026) | 36.6 GW (June 2026) | Waaree (~26 GW), Premier (11.1 GW), Adani (5.7 GW) | ALMM list of approved modules (~228 GW, Sept 2026) and cells (~35.5 GW); US is the main export market |
| Middle East | Under construction | Under construction | JA Solar (Oman: 6 GW cells, 3 GW modules), JinkoSolar (Saudi Arabia: 10 GW JV) | Access to the US and EU without Chinese origin |
Nameplate capacity; Mercom estimates India's operational capacity at 30–40% below nameplate. Sources: SEIA (Oct 2025), SEIA/Wood Mackenzie US Solar Market Insight Q2 2026, Mercom India H1 2026 via pv magazine, Energetica India, company filings.
The US gap is in cells. SEIA counted more than 60 GW of module assembly capacity in October 2025, but only about 3 GW of cells, and no new module capacity was added in Q1 2026. Six Asian countries supplied 78% of US cell imports. India's gap is narrower and closing faster: it added 50.6 GW of module and 9.7 GW of cell capacity in H1 2026 alone, and TOPCon makes up 80% of its approved module capacity. More on the duties is in our tariffs section.
Ukraine: An Import Market With One Local Maker
Ukraine installed about 1.5 GW of solar in 2025 and up to 1.1 GW in H1 2026, almost all of it with imported Chinese modules. China supplied 97.9% of the $273.2 million of panels imported in 2024, according to GTAIC trade data, and importer Atmosfera estimates that 2.5 GW arrived in 2025. The Solar Energy Association of Ukraine calls Embud LLC, which sells under the BLS brand, the only company in Ukraine making PV modules. It delivered 12 MW in its first year of serial production, 2025. Import VAT exemptions for modules, inverters and batteries run through 2028.
What Happened to the 2020 List
The 2020 version of this page listed 22 companies without ranking them. Several have since left the business, and the market has rewritten the rest of the order.
| Company on the 2020 list | Status in 2026 |
|---|---|
| SunPower | SunPower Corp. filed for Chapter 11 in August 2024. Its former manufacturing arm, Maxeon, has been under judicial management in Singapore since April 2026. The brand now belongs to Complete Solaria in the US and TCL SunPower elsewhere. |
| Panasonic | Ended its own cell and module production in 2021–22 and exited North American solar and storage in April 2025. |
| Sharp | Closed its European solar business on 31 March 2025. |
| Yingli | Restructured through a Chinese court in 2020; back in InfoLink's top 10 (No. 7 in H1 2026) and an RETC 2026 Overall Highest Achiever. |
| Canadian Solar | Still a top-10 shipper in 2025; dropped out of the top 10 in H1 2026 as it shifts to US factories and storage. |
| Hanwha Q Cells | Now Qcells, with the largest integrated US supply chain (Georgia). |
| REC | Owned by Reliance Industries since 2021; still makes heterojunction panels in Singapore. |
| Suntech, JS Solar, MUST Solar, Talesun, Samsung, Kyocera, Mage Solar, Schott | None appears in InfoLink's 2025 or H1 2026 rankings of the largest module suppliers. |
| Blueleaf Energy | A project developer rather than a panel manufacturer. |
Sources: SunPower investor relations, Maxeon filings via pv magazine USA, EnergySage and Solar Power World (Panasonic), pv magazine (Sharp), PV Tech (Yingli), InfoLink, RETC.
From Manufacturers to Models and Stocks
A manufacturer ranking answers who makes panels and who can afford to keep making them. It does not say which model to put on a roof. Our best solar panels of 2026 compares 12 current models on efficiency, Kiwa PVEL and RETC results and guaranteed output. For investors, most of the companies above are listed in Shanghai, Shenzhen, New York, Mumbai or Seoul. Our solar ETF overview shows which funds hold them.
Methodology and Data Sources
Selection and ranking. The ranking includes manufacturers with at least about 10 GW of 2025 module shipments that publish their results, plus Astronergy (InfoLink No. 6) and four manufacturers outside China that matter for buyers (Qcells, Waaree, Adani and Premier). Companies are ordered by company-reported 2025 shipments. InfoLink, whose rankings set the industry benchmark, publishes only tiers, so we use the companies' own figures and show InfoLink's H1 2026 rank alongside.
Shares and margins. Shares of world shipments divide each company's 2025 volume by ITRPV's 706 GW of global module shipments. JA Solar's figure includes cells and Tongwei's reflects module sales, so their shares are indicative. Net margins divide net profit or loss attributable to shareholders by revenue, in each company's reporting currency, so no exchange rate is needed. The CNY 25 billion combined loss converts to about US$3.6 billion at the RMB 6.99 per dollar rate JinkoSolar used in its 2025 results. Indian companies report for April 2025–March 2026.
What we left out. We excluded figures we could not trace to a company filing or a primary dataset. That includes 2025 capacity for Trina, Tongwei, Astronergy and Aiko, Yingli's financials, Wood Mackenzie's ranks 2 to 5 (published only as an image) and BloombergNEF Tier 1 counts for 2026 reported only by distributors. list.solar receives no payment from any company listed, and this page contains no affiliate links. Updated: October 2026.
FAQ
Is the biggest solar panel manufacturer the best one to buy from?
Not by default. The four largest shippers, JinkoSolar, LONGi, Trina and JA Solar, lost about CNY 25 billion in 2025, while First Solar, Waaree, Premier and DMEGC made profits. Size brings research and service scale, but a 25-year warranty depends on financial health. For product quality, check model-level Kiwa PVEL and RETC test results.
Who is the largest solar panel manufacturer in 2026?
JinkoSolar and LONGi are tied. JinkoSolar shipped 86.8 GW of modules in 2025 and LONGi 86.58 GW. InfoLink ranked them joint first in both 2025 and H1 2026. Wood Mackenzie, which also weighs financial health and technology, put LONGi first in its 2026 manufacturer ranking.
Which solar panel manufacturers are profitable?
In 2025, First Solar earned $1.53 billion (net margin 29.3%), Premier Energies 18.8%, Waaree 14.6% and DMEGC 8.2%. Every other large Chinese module maker reported a net loss, from −7.6% at GCL SI to −31.7% at TCL Zhonghuan. Canadian Solar lost 1.9%. Wood Mackenzie estimates Chinese makers lost $5.5 billion combined.
Where are solar panels made outside China?
India has the largest base, with 261.7 GW of module and 36.6 GW of cell capacity in June 2026. The US had more than 60 GW of module capacity but only about 3 GW of cells. Southeast Asia hosted many Chinese-owned plants, though US duties cut US imports from Cambodia, Malaysia, Thailand and Vietnam from $12.2 billion in 2023 to $1.3 billion in 2025. Oman and Saudi Arabia have plants under construction.
Are any solar panels made entirely in the USA?
Few. First Solar makes thin-film modules from raw materials in Ohio, Alabama and Louisiana. Qcells started US cell production at Cartersville, Georgia, in June 2026, adding ingot and wafer lines to its 8.6 GW of module assembly. Most other US plants assemble modules from imported cells, since US cell capacity was only about 3 GW in early 2026.
Related on List.Solar
- Best Solar Panels (2026 Data): 12 models compared on efficiency, reliability and warranty
- Best Solar Inverters: the other half of a solar system
- Top Renewable Energy Stocks: listed companies across the sector
- Solar Manufacturing News: factory openings, closures and trade cases
Sources
- InfoLink, 2025 global module shipment ranking, 27 Feb 2026; H1 2026 ranking, 14 Aug 2026; 2024 ranking
- ITRPV 17th edition via TaiyangNews, 706 GW shipped in 2025; ITRPV 16th edition
- IEA PVPS Trends 2026 via pv magazine, Global solar additions hit 690 GW in 2025, 29 Sep 2026
- Wood Mackenzie, Global Solar PV Module Manufacturer Ranking 2026, 2 Jun 2026
- JinkoSolar, Q4 and full-year 2025 results; full-year 2024 results; pv magazine, Saudi Arabia joint venture, 27 Aug 2024
- LONGi, 2025 annual report; TaiyangNews, LONGi FY2025 results
- EnergyTrend, 2025 results of Chinese PV makers (Trina, Tongwei, Aiko, Jinko, Risen), 30 Apr 2026, and JA Solar 2025; TaiyangNews, JA Solar 2024 and JA Solar H1 2026
- TaiyangNews, DMEGC FY2025 and TCL Zhonghuan FY2025; Eastmoney, GCL SI 2025 results
- Canadian Solar, full-year 2025 results (SEC 6-K); full-year 2024 results
- First Solar, Q4 and full-year 2025 results (8-K), 24 Feb 2026; 2025 annual report; Energetica India, First Solar withdraws ITC patent case
- pv magazine, Qcells begins cell production in Cartersville, 10 Jun 2026; pv magazine USA, Qcells furloughs 1,000 Georgia workers, 10 Nov 2025; Asiae, Hanwha Solutions Q1 2026
- TaiyangNews, Waaree Energies FY2026 and Premier Energies FY2026; Mercom, Waaree Q4 FY2026 and Premier Q4 FY2026; Adani Enterprises, Q1 FY27 results
- JUVE Patent, Maxeon and Aiko settle solar panel dispute, Feb 2026; SMM, Trina completes sale of 5 GW US factory to T1 Energy; Canal Solar, Astronergy capacity plans; Chint, Chint Electric 2025 annual report
- SEIA, US solar manufacturing capacity, Oct 2025; SEIA/Wood Mackenzie, US Solar Market Insight Q2 2026
- pv magazine, India added 50.6 GW of module capacity in H1 2026 (Mercom), 25 Sep 2026; Mercom, India capacity additions in 2025; Energetica India, ALMM update, Sept 2026
- pv magazine USA, Final duties on India, Indonesia and Laos, 11 Sep 2026; pv magazine India, ITC injury vote, 16 Oct 2026; Wiley, Section 232 tariffs and minimum import prices, Aug 2026, and ITC vote on Southeast Asian duties, May 2025
- OPIS via pv magazine, TOPCon prices, 16 Oct 2026; pv magazine, polysilicon consolidation halted, Jan 2026; Henan Provincial Government, export VAT rebate cancellation, 10 Jan 2026; SolarPower Europe, Global Market Outlook 2026–2030, Jun 2026
- PV Tech, Yingli restructuring approved; SunPower, Complete Solaria rebrands as SunPower, 22 Apr 2025; pv magazine USA, Maxeon restructuring filing, 6 Apr 2026; Solar Power World, Panasonic quits solar, Apr 2025; pv magazine, Sharp withdraws from European solar, 6 Feb 2025
- Ukraine: pv magazine, Ukraine adds 1.1 GW in H1, 23 Sep 2026; SEAU, Embud LLC domestic module production, Mar 2026; GTAIC, PV modules market, Ukraine; Delo.ua, Ukraine imported 2.5 GW of panels in 2025